See The Scheduled Interest Dollars
Use an amortization schedule to identify projected scheduled-interest dollars for the period you are analyzing.
A strong income, real equity, and on-time payments can still leave a family squeezed when the mortgage structure controls the cash flow
Get Instant Access For $14.99 See What's InsideDigital edition • PDF | Immediate digital PDF delivery
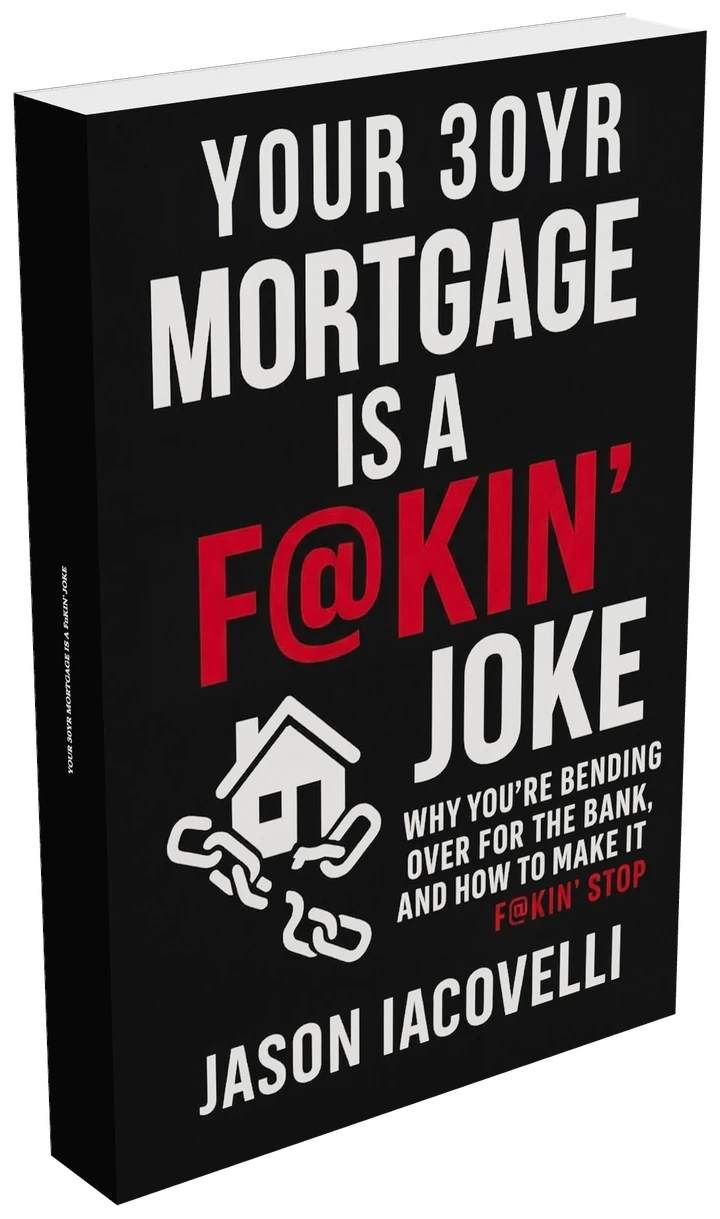
I entered mortgage lending at 22 because I was broke, stubborn, and ready to work. Just before I turned 23, I was diagnosed with cancer, and I kept working through chemotherapy.
That year changed my relationship with fear. Years later, it mattered when I kept seeing a quieter problem repeat itself. Smart homeowners earned good money, made scheduled payments for 5, 10, or 15 years, and still felt squeezed while the principal moved more slowly than they expected.
Maybe you know the feeling of watching your checking balance shrink long before the next paycheck arrives. Maybe you know the Sunday night math where your income looks strong on paper but your available cash tells a different story. Maybe you have built real equity while struggling to build liquid savings. Maybe you have followed the conventional mortgage script and wondered why responsible behavior still feels so tight.
Your income is real. Your equity is real. Your on-time payments are real.
The question that changed my work was simple. What happens when household income can reduce a qualifying daily-interest balance while that money remains available for normal expenses?
The answer changed the scoreboard, and it became the reason I wrote this book.
My name is Jason Iacovelli.
I learned the mortgage business from inside it, and over time I saw how often the conversation centered on rate and scheduled payment. Those numbers matter, but they do not show the entire borrowing cost or explain why a strong income can still leave a household cash-flow squeezed.
Over time, the pattern became impossible for me to ignore. Homeowners who had paid for years could still owe far more principal than they expected. At the same time, household income often sat in a separate checking account until bills were paid.
That observation led me to examine a different structure. The UnMortgage combines a homeowner's income and mortgage in 1 automated daily-interest account. Income reduces the outstanding balance when it arrives, expenses come back out as needed, and interest is calculated from the resulting daily balance under the account's terms.
The important discovery was structural. Money that remains against a qualifying daily-interest balance can reduce the interest charged for those days.
The actual benefit depends on qualification, product terms, fees, rate changes, posting rules, access to funds, and household cash flow.
I built this book so homeowners could understand that complete picture, compare it fairly with their current mortgage, and ask better questions before changing anything.
That work became the reason I wrote this book.
You followed a familiar script. Compare rates, choose a scheduled payment you can afford, keep income in checking or savings, and make every payment on time.
That script can leave important numbers outside the conversation.
First, rate alone does not show total scheduled interest. A conventional fixed-rate mortgage uses an amortization schedule that divides each monthly principal-and-interest payment between interest and principal. Early in the schedule, more of the payment generally goes to interest because the outstanding principal is higher. The actual split depends on the loan amount, rate, term, and payment number.
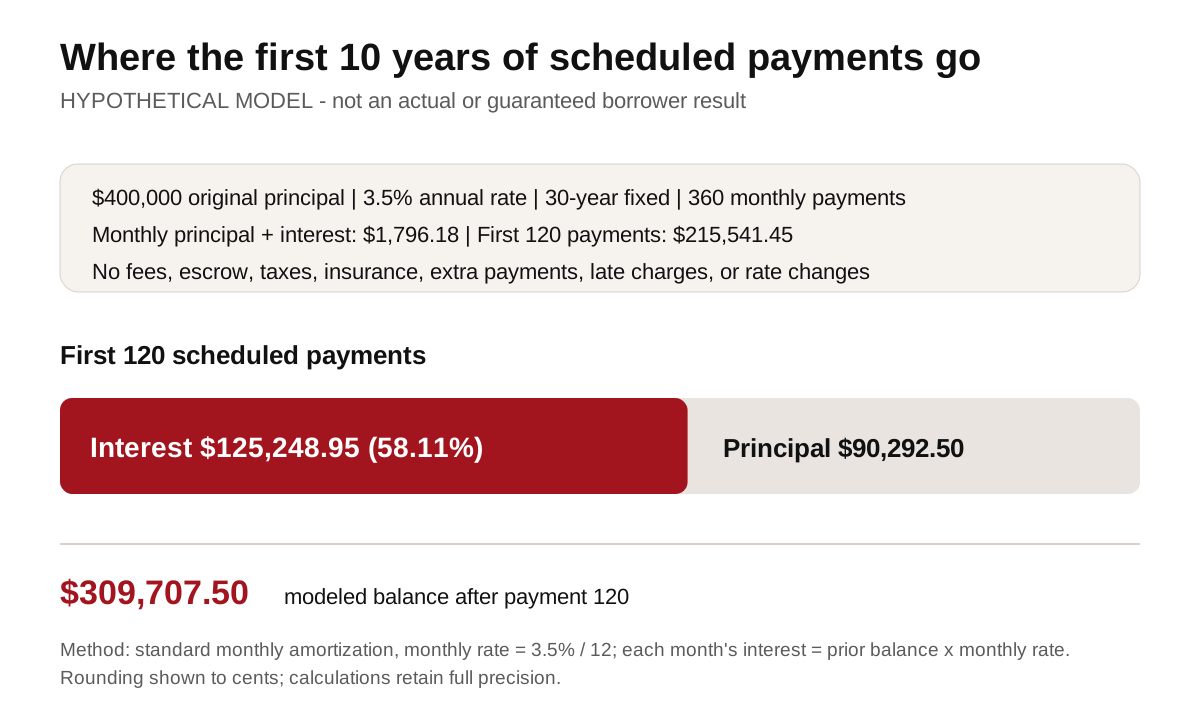
Second, the monthly payment does not show the cost in hours of your working life. Your amortization schedule can show projected scheduled-interest dollars. Dividing those dollars by after-tax hourly earnings converts the same cost into work-hours and 40-hour workweeks.
Third, cash held in checking remains liquid, but it does not reduce a separate conventional mortgage balance. A qualifying daily-interest account creates a different relationship between available cash and debt, although that relationship must be evaluated against fees, variable-rate exposure, home-secured risk, liquidity needs, and the terms of the current mortgage.
Your effort deserves a complete scoreboard.
The right next step is to understand the math before deciding whether any change fits your household.
A strong income can still feel tight when the mortgage and household cash flow operate in separate accounts.
The UnMortgage combines income and mortgage in 1 automated daily-interest account. When income arrives, it reduces the outstanding balance. Expenses come back out as needed. Interest is calculated from the outstanding daily balance, subject to the contract's rate, fees, posting rules, and other terms.
That means funds can work against the balance while they remain in the account, and normal expenses can still be paid from available credit or account access as the product permits.
Automation can reduce the manual transfer and timing work that some cash-flow strategies require. It does not remove the need to qualify, maintain sufficient cash flow, understand variable-rate and home-secured risk, preserve appropriate liquidity, and compare the full cost with the current mortgage.
For some homeowners, the current mortgage may remain the better choice. For others, a qualifying daily-interest structure may deserve closer analysis.
Your 30yr Mortgage is a F@KIN' Joke gives you the framework to understand the difference before you act.

My reason for questioning the conventional script comes from my own story. I entered mortgage lending at 22, worked through cancer and chemotherapy, and later focused on the pattern of homeowners making scheduled payments while their principal moved more slowly than they expected.
The proof offered here is the logic you can reproduce.
A product that uses daily simple interest calculates interest from its outstanding daily balance. When income reduces that balance, the interest charged for each day is based on the lower balance until expenses or other draws increase it again. The size of any difference depends on the balance, rate, number of days, fees, posting rules, draws, and household cash-flow pattern.
You can test that relationship without relying on a testimonial. Read the product terms. Record the daily balances. Apply the stated rate and day-count method. Include fees and rate changes. Then compare that result with the scheduled cost and remaining term of the current mortgage.
The book shows you what to inspect and what assumptions to label. Your own documents and arithmetic decide whether the structure deserves another look.
Use an amortization schedule to identify projected scheduled-interest dollars for the period you are analyzing.
Divide scheduled-interest dollars by after-tax hourly earnings, then convert the result into 40-hour workweeks.
Evaluate rate, total scheduled interest, payment structure, fees, term, and the principal-versus-interest split together.
See how a qualifying product calculates interest from the outstanding daily balance under its contract terms.
Compare cash held separately with cash applied against a daily-interest balance while accounting for liquidity and access needs.
Use transparent inputs to compare the current mortgage with a qualifying alternative, including costs, risks, assumptions, and the possibility that the current mortgage is the better fit.
The stated value of the digital edition of Your 30yr Mortgage is a F@KIN' Joke is $24.99.
Today the price is $14.99, delivered as a digital PDF.
That is 40% below the stated value. For less than many familiar household purchases, you can get a numbers-first framework for examining 1 of the largest financial obligations in your life.
Digital edition • PDF
One-time price · Plus applicable tax · Payment processed by MyLO Media through Stripe
Read the digital book and use the framework to examine your mortgage documents.
If you decide within 30 days of purchase that the book was not worth the $14.99 price, request a refund and the purchase price will be returned under the offer terms.
The promise is simple. Love It Or Pay Nothing.
The value of reading now is clarity. You can understand the scheduled cost, the labor calculation, and the daily-interest mechanism before deciding whether your current structure should remain unchanged.
You can keep measuring the mortgage mainly by rate and scheduled payment, or you can open the book and examine the complete structure.
Start with your amortization schedule. Find the scheduled-interest dollars for the period you want to analyze. Convert that amount into after-tax work-hours. Learn how a qualifying daily-interest account works. Then compare the current mortgage with any alternative using the same visible assumptions.
You have earned the right to understand where the money goes.
You have made the payments.
Now you can read the full scoreboard before making another decision.
Get Instant Access For $14.99